

MoBill Budget and Reminder
4.0

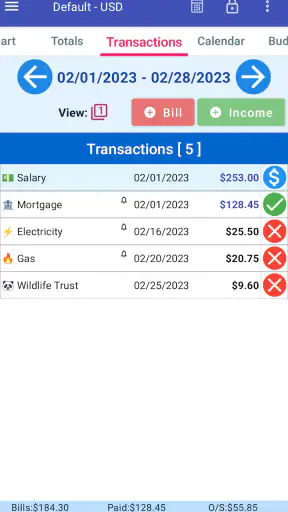
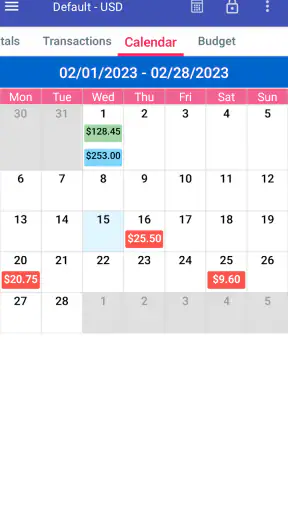
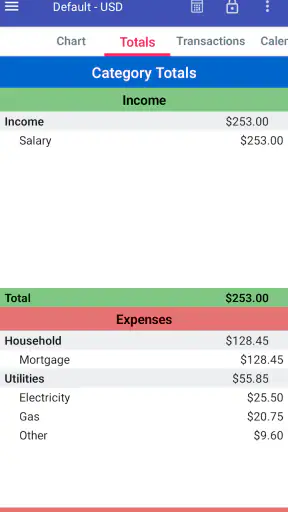
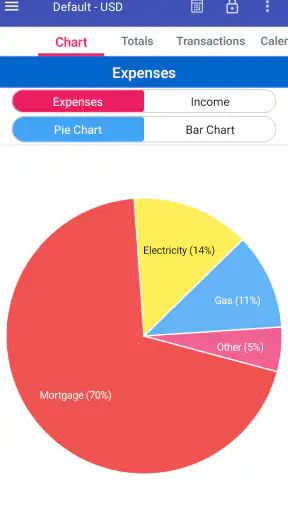
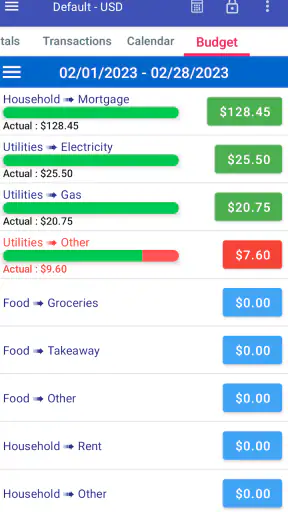
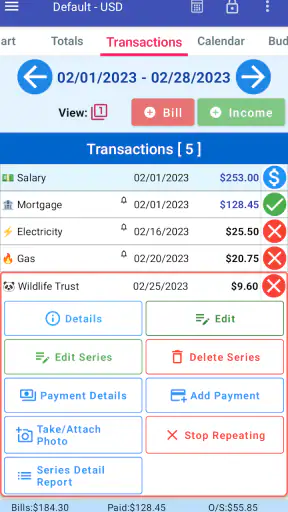
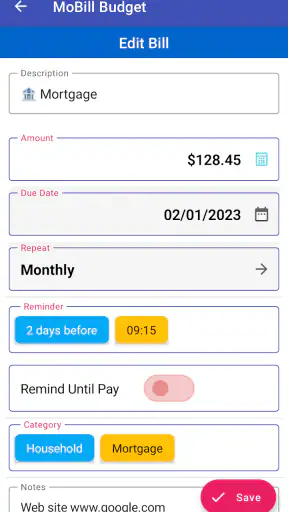
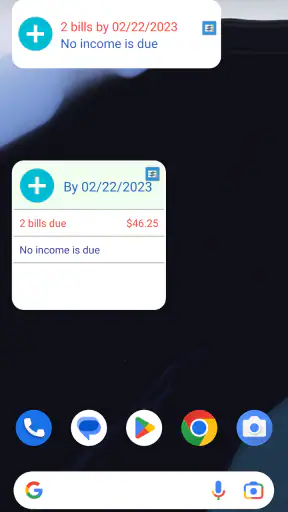
Managing bills sounds simple until several due dates, irregular paydays, and everyday spending start competing for attention. I tried MoBill Budget and Reminder with that practical problem in mind, and I found a finance app that is more useful as a personal routine than as a complete banking command center. It is built for keeping bills and a household budget visible, especially when I want a straightforward place to remember what needs attention.
The app comes from MoBill Apps and is free to download, with optional in-app purchases ranging from $2.50 to $10.99 per item. It is rated for Everyone, runs on Android 8.0 and later, and the current version is 5.3.1. Its long presence on the platform is reflected in more than 500K installs, while its average rating sits at 4.0 from around 3.8K ratings. Those figures suggest a familiar, established tool rather than a brand-new budgeting experiment, but they do not remove the need to see whether its approach fits your habits.
Where the real friction begins
The first challenge is not usually entering a bill. The harder part is deciding how consistently I will maintain the information afterward. A reminder app only helps when the amount, date, and payment status remain current. If I add a few obligations and then stop updating them, the screen can create a false sense of control. MoBill Budget and Reminder works best when I treat it as a short daily or weekly check-in, not as an automatic replacement for checking my bank account.
That distinction matters because a budget tool and a bank connection solve different problems. A bank app shows transactions that have already happened. MoBill is more useful for planning what I expect to happen next. I can use it to keep upcoming obligations in view, while my bank remains the place to verify whether a payment actually cleared. Keeping those roles separate prevents one of the most common mistakes: assuming that recording a bill means the bill has been paid.
Users can also get stuck when they try to model every financial detail immediately. I recommend beginning with the obligations that could cause the most trouble if forgotten: housing, utilities, insurance, loan payments, subscriptions, and other recurring commitments. Once that basic list feels reliable, I would add less important items. Starting with a complete financial history may feel thorough, but it often creates more maintenance than value.
Another source of friction is irregular income. A simple reminder schedule is easy to understand when a bill arrives on the same day each month. It becomes less comfortable when income changes, payment dates move, or a bill varies substantially. In those cases, the app can still serve as a checklist, but I would avoid treating its planned figures as a precise forecast unless I review them against current statements.
Why the first setup deserves patience
On first use, I would prepare a small list before opening the app: the name of each recurring bill, its usual due date, the amount or a sensible estimate, and the account or payment method I normally use. This makes the setup less frustrating because I am not trying to remember everything while moving between screens. It also gives me a chance to notice duplicate subscriptions or bills that have quietly changed.
I would enter fixed obligations first and variable ones second. A rent payment or fixed membership is easy to plan. Electricity, phone usage, and similar changing expenses need a little more judgment. For those, I would use a realistic recent amount rather than an unusually low month. The goal is not to make the budget look comfortable; it is to make the reminder useful when the month becomes busy.
A helpful habit is to choose one consistent naming style. “Internet,” “Mobile,” and “Streaming” are easier to scan than long descriptions that include every billing detail. If two payments belong to the same provider, adding a short distinction such as “home” or “work” can prevent accidental edits. This is a small organizational choice, but it becomes important once the list grows.
I also recommend checking dates carefully instead of assuming that a recurring payment always lands on the same calendar day. Weekends, holidays, and provider-specific processing can change when money leaves an account. MoBill can remind me about the expected obligation, but I still need to understand the actual payment schedule. A reminder set for the wrong day is worse than no reminder because it creates misplaced confidence.
Setup checks that prevent avoidable confusion
Before relying on the app, I would perform a short test with one upcoming bill. I would confirm that the entry appears where I expect it, that its amount is sensible, and that the reminder timing matches my real routine. If I usually need two or three days to move money between accounts, a notification on the due date is too late. The right reminder is the one that gives me enough time to act, not merely enough time to notice.
I would also check the phone’s general notification behavior if a reminder does not appear. Notification settings, silent modes, battery-saving rules, and an app that has not been opened for a long time can all affect alerts. These are phone-level issues rather than proof that the budgeting logic is wrong. A quick test reminder is more useful than waiting for an important bill to reveal the problem.
Another sensible check is whether the phone has enough available storage and whether the installed version is current. MoBill supports Android 8.0 and later, so an older device may be outside the supported range. If the app opens but behaves strangely, I would first restart the phone and check for an available update before rebuilding the entire budget.
Because the app is free with optional purchases, I would pay attention to which functions are available in the basic experience and which require an upgrade before building my entire routine around them. I would not purchase anything simply to solve a setup mistake. First I would identify whether the problem is an incorrect entry, a notification setting, or a limitation of the selected version.
Recovering when the workflow goes wrong
Missed reminders are not a reason to abandon the system. My preferred recovery method is to reconcile from the current bank balance and recent statements, then mark only what I can verify. I would avoid guessing that several old entries were paid merely because the dates have passed. A clean, honest starting point is more valuable than a detailed history filled with assumptions.
If an amount looks wrong, I would edit the individual bill rather than deleting everything and starting again. Before making changes, I would compare the entry with the latest statement or provider notice. Variable bills can make a budget appear inaccurate even when the original reminder was entered correctly. In that situation, the fix is to update the expected amount for the next cycle, not to treat the earlier estimate as an error.
When a recurring item becomes confusing, I would temporarily simplify it. For example, I might keep one clear reminder for the obligation and record the latest expected amount, rather than creating several near-identical entries for every variation. This reduces the chance of double-counting. A smaller, dependable list is more useful than a detailed list that I no longer understand.
If the app stops responding, I would use the least disruptive troubleshooting order: close and reopen it, restart the device, check the available update, and review whether the issue affects one entry or the whole app. I would be cautious about clearing app storage or uninstalling before confirming that I can recreate my entries. Destructive troubleshooting should be the last step, especially for a finance tool where manually rebuilding data can be tedious.
For a forgotten password or account-related problem, I would use the app’s own recovery path rather than repeatedly guessing credentials. I would also avoid entering sensitive banking details into notes or labels. A bill reminder is not the same as a secure bank ledger, and keeping unnecessary account information out of the app is a sensible privacy habit.
A realistic month with MoBill
Imagine that I am paid near the end of the month, while rent, a phone bill, insurance, and several subscriptions arrive during the first two weeks. I would open MoBill shortly after payday, review the upcoming obligations, and compare the total expected outflow with the balance available for bills. I would then check the bank app separately to confirm that the previous cycle’s payments cleared. This two-step routine takes less time than chasing a forgotten payment later.
Mid-month, I would use the app as a prompt rather than a financial verdict. If a utility bill is higher than expected, I would update my plan and decide whether another discretionary expense needs to wait. If a subscription is no longer useful, the reminder can expose it as part of the monthly pattern, but cancellation still has to happen with the provider. The app helps me notice the obligation; it does not perform every financial action on my behalf.
At the end of the cycle, I would spend a few minutes closing the loop. I would check which reminders correspond to completed payments, correct changed amounts, and remove anything that is no longer relevant. This is where the app’s value grows: not from one impressive setup session, but from repeatedly keeping the list aligned with real life.
When the app is not the cause
Budgeting problems are often blamed on the app when the underlying issue is incomplete information. A payment may be pending at the bank, a merchant may have changed its billing date, or a card statement may group several transactions differently from the way I entered them. MoBill cannot know those changes unless I update the record. If the numbers disagree, I would compare the app with the original statement before assuming that the reminder is malfunctioning.
Notifications can also fail for reasons outside the app itself. A phone in Do Not Disturb mode, restricted background activity, or an aggressively managed battery profile may delay alerts. I would test the notification after reviewing those settings. If other apps are also missing alerts, the wider phone configuration is the more likely place to investigate.
There is a similar issue with budgeting expectations. If I want automatic transaction categorization, investment analysis, shared household access, or a complete account aggregation service, I would look at a more specialized personal finance platform. MoBill’s appeal is its focused reminder-and-budget role. Expecting it to behave like a full banking dashboard can make a suitable app seem inadequate.
The app is also not the best match for someone who never wants to enter or review information manually. Its usefulness depends on my willingness to maintain the plan. A person who prefers automatic synchronization may be happier with a service designed around linked accounts, even if that means accepting more complexity, permissions, or subscription costs.
How it compares with familiar alternatives
Compared with a paper planner, MoBill gives me a more active way to keep recurring obligations visible and adjust amounts as circumstances change. Paper can be calming and private, but it is easy to overlook when I am away from the notebook. The app is better for a phone-centered routine, while paper may suit someone who enjoys a weekly desk review.
Compared with a spreadsheet, MoBill is less flexible but easier to approach for a simple bill schedule. A spreadsheet can handle detailed categories, custom formulas, long-term comparisons, and unusual income patterns. It also demands more design and maintenance. I would choose a spreadsheet when I need deep analysis; I would choose MoBill when the main goal is remembering and reviewing regular obligations without building a financial model.
Compared with a bank app, MoBill is more forward-looking for planned bills, while the bank remains more authoritative for completed transactions and account balances. I would use both rather than asking one to replace the other. That combination is particularly useful for people who have several accounts or whose bills do not all leave the same place.
Compared with a highly automated budgeting service, MoBill may feel simpler and less intrusive, but it may also require more personal upkeep. Automation saves time when it works smoothly. Manual control is valuable when I want to decide exactly what belongs in the budget and do not want every transaction interpreted for me. The better choice depends on whether I value convenience or direct control more.
Who will get the most from it
I think MoBill Budget and Reminder is a good fit for someone who repeatedly forgets due dates, wants a dedicated place for household obligations, or is trying to establish a basic budgeting ritual. It can also help people with several subscriptions because seeing them together makes recurring costs easier to question. The app’s Everyone age rating makes it approachable for a broad household audience, although financial responsibility still depends on the person using it.
It is less suitable for a user who needs sophisticated reporting, automatic bank feeds, collaborative household budgeting, or detailed investment tracking. It is also a weak fit for someone whose finances change so rapidly that a manually maintained schedule becomes outdated every few days. In those situations, another category of finance tool would probably save more time.
My strongest practical tip is to keep the system deliberately modest. Add the bills that matter, set reminders early enough to act, verify payments through the bank, and review the list once a week. Do not turn every small purchase into a budgeting project unless that level of detail genuinely helps you. The app becomes more dependable when it supports a routine I can sustain.
My practical verdict
After using it as a planning companion rather than a replacement for a bank, I see MoBill Budget and Reminder as a focused, approachable finance app with a clear everyday purpose. Its free entry point makes it easy to try, and the optional purchases give users a way to consider extra value without making the basic decision feel complicated. The 4.0 average and its substantial user base suggest that many people find the concept useful, though the experience will still depend heavily on personal organization.
The key trade-off is simple: you gain control and clarity, but you must supply the discipline. If I am willing to keep dates and amounts current, the app can reduce the mental load of remembering recurring obligations. If I expect automatic financial intelligence or a complete picture of my accounts, I would choose a more advanced alternative instead.
For a friend who wants a lightweight reminder-centered budget, I would recommend giving it a careful trial on Android 8.0 or later, starting with a few important bills and testing the reminder routine before entering everything. That approach reveals its strengths quickly and avoids the most common setup trap: confusing a neatly organized list with a fully verified financial record.
4.0
1.56K Reviews
Pros
- Simple budget tracking for everyday spending
- Helpful reminders reduce the chance of missed payments
- Clear overview of upcoming bills and expenses
- Useful for organizing recurring financial obligations
- Lightweight design is easy to navigate
Cons
- May lack advanced investment and debt management tools
- Manual entry can become time-consuming for frequent purchases
- Reminder features depend on accurate dates and amounts
- Limited sharing options may not suit households
- Some features may require payment or contain ads


